TRW & Co · Customs and trade
How to Clear Goods at Chattogram Custom House
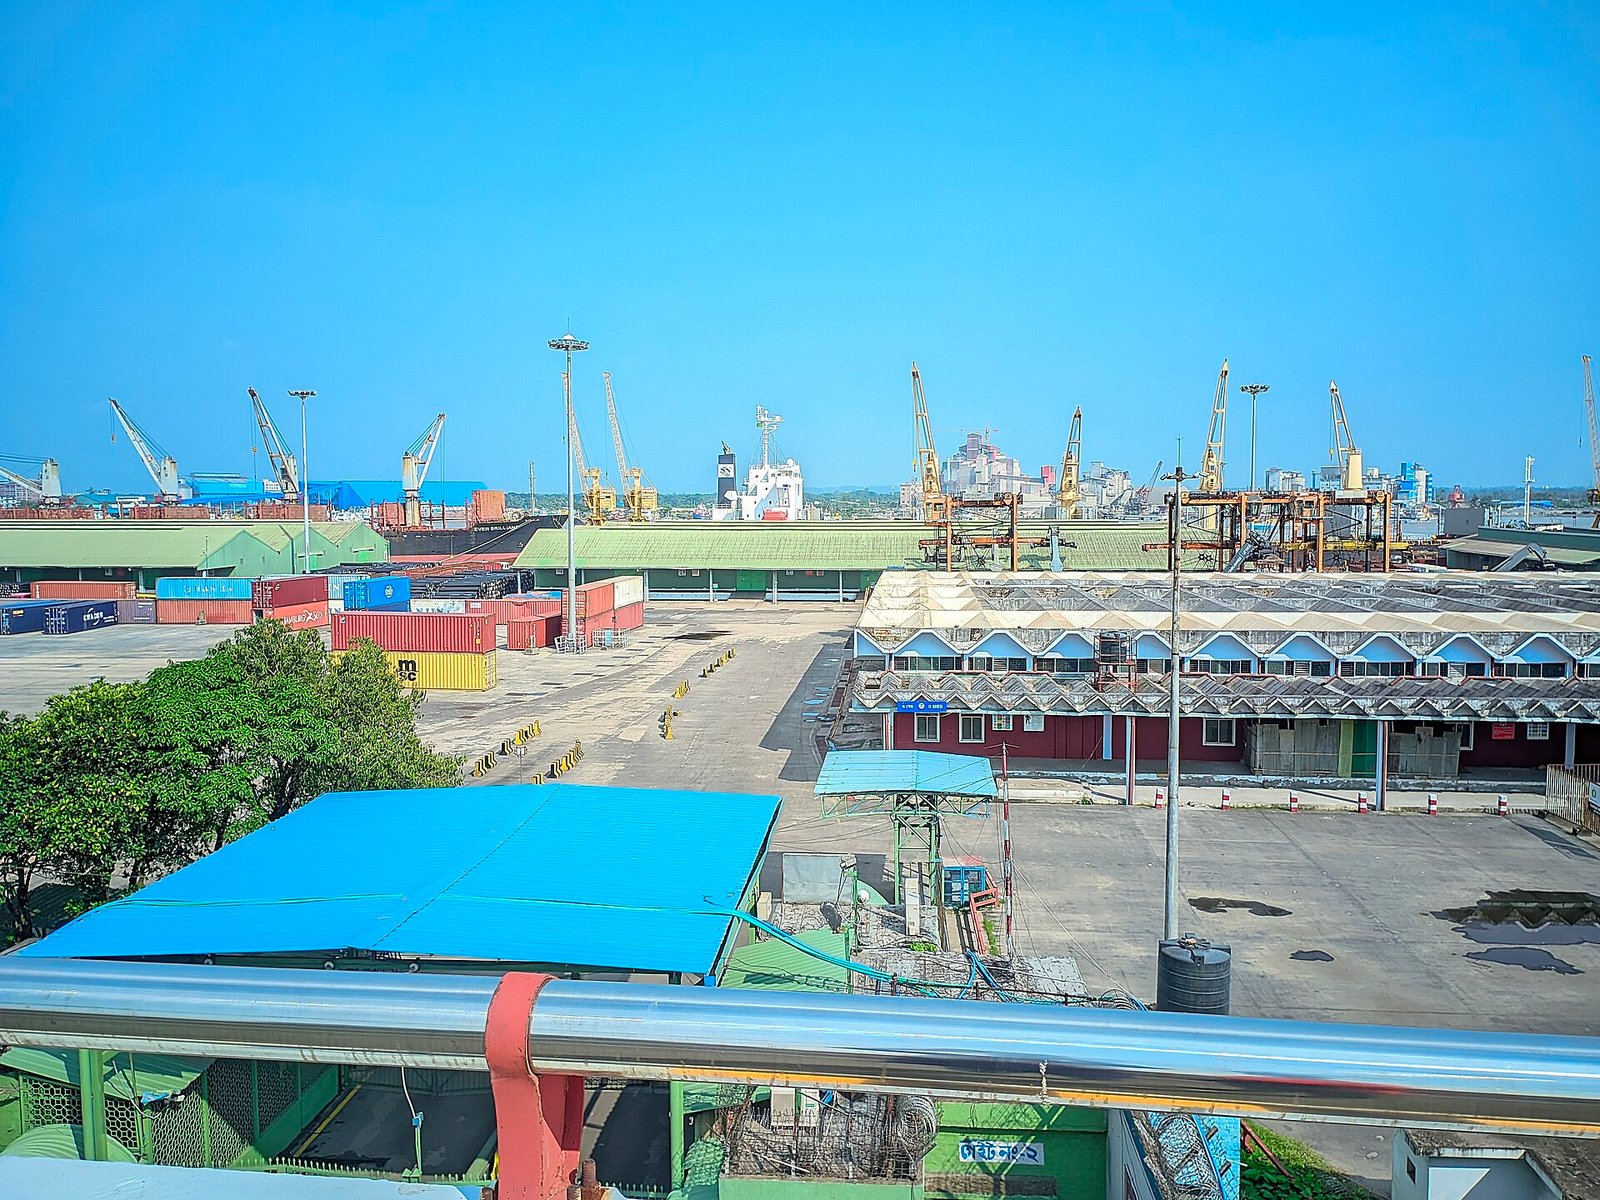
Here is how to clear goods at Chattogram Custom House in 2026: lodge a bill of entry in ASYCUDA World, let customs assess value and HS code, clear any examination, pay duties and taxes, and collect the release order before port delivery. The Customs Act 2023 sets deadlines that protect importers, but most delays start with inconsistent documents.
Key pointIf correctly declared goods are not assessed within seven working days, section 95 of the Customs Act 2023 lets the importer serve notice on the Commissioner, who must then assess the goods or issue a show cause notice.
At a glance
Governing law
The Customs Act 2023 replaced the Customs Act 1969 from 6 June 2024 and governs declarations, assessment, examination, release and post-clearance audit at Chattogram.
Filing window
The bill of entry must be lodged within five working days of unloading; a pre-arrival declaration is allowed where the vessel is expected within 30 days.
Payment period
Duties are payable within ten days of notification unless another date is given, with interest at one per cent a month on late payment.
Provisional release
Where tests or documents are pending, goods can be released on provisional assessment against a guarantee, with final assessment due within 120 working days.
Agent responsibility
Licensed C&F agents share responsibility for the accuracy of declarations, and their acts are presumed to have the importer's knowledge and consent.
Swipe or scroll →
The short answer: how to clear goods at Chattogram Custom House
If you are working out how to clear goods at Chattogram Custom House, the sequence is fixed by the Customs Act 2023 and the ASYCUDA World system. The importer or its licensed C&F agent lodges an electronic bill of entry, customs assesses value, classification and origin, the goods may be examined or sampled, duties and taxes are paid, and customs issues a release order. Only then can the goods leave the port or off-dock depot.
Most delays are not caused by the law but by the paperwork behind the bill of entry. An invoice that does not match the letter of credit, a missing permit, a vague description or an HS code chosen in haste can turn a routine clearance into a hold, a reassessment or a seizure. This guide explains each stage, the legal deadlines that protect importers, and the mistakes we see most often in Chattogram.
As of October 2026, clearance runs under the Customs Act 2023 (authentic English text), which replaced the Customs Act 1969 from 6 June 2024. For disputes that go beyond clearance, see our customs lawyers in Chattogram.
The legal framework for customs clearance
The Customs Act 2023 sets out the core duties of importers and the powers of customs officers. The Act requires a declaration of goods in the customs computer system stating the customs procedure, the classification, the country of origin, the customs value, the quantity and a proper description (section 81). The person making the declaration, and any agent who files it, is responsible for its correctness and for producing documents when asked (section 82).
Assessment rules sit in sections 90 to 98. They cover assessment, reassessment, release, provisional assessment, goods deemed handed over to the government and the procedure where goods are not assessed in time. Valuation follows section 27, which takes the price actually paid or payable as the starting point. The National Board of Revenue (NBR) publishes rules, general orders and statutory regulatory orders (SROs) that fill in the detail, and annual finance laws amend the Act.
Import permissions come from outside the Customs Act. An importer normally needs an Import Registration Certificate, a VAT registration with a Business Identification Number (BIN), and any product-specific clearance required by the Import Policy Order. The Bangladesh Customs import procedure lists the usual supporting documents, including the letter of credit, invoice, bill of lading, packing list, certificate of origin, insurance cover and BIN certificate. Our guide to IRC and ERC import licensing covers registration.
Who does what in Chattogram
- Chattogram Custom House receives the bill of entry, assesses duties, orders examination and issues the release order.
- Chittagong Port Authority controls the terminals, yards and delivery of containers and charges port rent once free time ends.
- Shipping lines and their agents file the import manifest, issue delivery orders and charge container detention.
- Licensed C&F agents prepare and file the bill of entry, attend examination and pay duties on the importer's behalf.
- Off-dock container depots handle many containers that are moved out of the port for examination and delivery.
How to clear goods at Chattogram Custom House, step by step
The steps below show how to clear goods at Chattogram Custom House under the Customs Act 2023 and the published Bangladesh Customs import procedure. Timing depends on the risk channel, the goods and how complete the file is, so treat this as the legal skeleton rather than a timetable.
- Check permissions before shipment. Confirm the IRC is valid, the goods are importable under the current Import Policy Order, and any permit, test certificate or quarantine clearance is in hand. Fixing a missing permit after arrival is the single biggest cause of avoidable port rent.
- Align the commercial documents. The invoice, packing list, bill of lading, letter of credit and certificate of origin must describe the same goods, quantity and value. Ask the supplier for a description precise enough to support the HS code you will declare.
- Lodge the bill of entry in ASYCUDA World. The importer or its C&F agent files the declaration electronically once the import manifest is in the system. Under section 84 it must be filed within five working days of unloading, and a pre-arrival declaration may be lodged if the vessel is expected within 30 days.
- Assessment of value, classification and origin. Under section 90 the assessing officer determines the HS classification, origin and customs value and calculates duties and taxes. Where a final figure is not possible, section 93 allows provisional assessment and release against a guarantee.
- Examination, sampling and testing. Customs may inspect documents, scan the container, physically examine the goods or draw samples for laboratory testing (sections 87 and 88). The importer bears the cost of opening, handling and testing under section 89.
- Pay duties and taxes. Customs duty, regulatory duty, supplementary duty, import VAT, advance income tax and advance tax are paid through the approved banking channels. Section 32 makes duties payable within ten days of notification unless another date is given.
- Release order and port delivery. Once duties are paid and the declaration is accepted, customs issues the release order (section 92). The agent then settles port and depot charges and the shipping line's delivery order, and the goods leave the gate.
Knowing how to clear goods at Chattogram Custom House also means knowing the protective deadlines. If properly declared goods are not assessed within seven working days, section 95 lets the importer serve notice on the Commissioner, who must then assess or issue a show cause notice. Detained, seized and adjudicated goods are excluded from this rule.
Clearance routes compared
Not every consignment follows the same path, and part of knowing how to clear goods at Chattogram Custom House is choosing the right one. The Act gives customs and importers several procedural options, and the right choice depends on the goods, the documents and how urgently they are needed.
| Route | When it fits | Key condition | Watch for |
|---|---|---|---|
| Normal assessment and release | Complete documents, settled HS code and value | Duties paid in full | Selection for examination can still add time |
| Pre-arrival declaration | Vessel expected within 30 days | Declaration lapses if goods do not arrive in time (section 84) | Errors found later are harder to amend |
| Provisional assessment | Test results, documents or enquiries outstanding | Guarantee for the possible difference (section 93) | Final assessment due within 120 working days, extendable |
| Into a warehouse | Goods not needed immediately or for re-export | Warehousing bond or bank guarantee | Warehousing periods are set by the NBR |
| Authorised Economic Operator | Established, compliant traders | AEO status granted by the NBR (section 97) | Simplified formalities depend on AEO class |
| Release under protest, then appeal | Dispute over value or HS code but goods urgently needed | Pay assessed duty and record objection in writing | Appeal deadlines run from the order |
For value and classification disputes, our guide on how to challenge a customs valuation explains the evidence that works. For export-oriented manufacturers using bonded inputs, see bonded warehouse rules.
The role of the C&F agent
For most businesses, the practical answer to how to clear goods at Chattogram Custom House is to appoint a licensed customs clearing and forwarding (C&F) agent. Section 243 of the Customs Act 2023 bars anyone from acting as an agent at a customs station without a licence, and the NBR replaced the 2020 licensing regulations with the Customs Clearing and Forwarding (C&F) Agent Licensing Regulations 2026, gazetted in January 2026.
The agent's acts bind the importer. Under section 245, anything done by an authorised agent is presumed to have been done with the owner's knowledge and consent unless the contrary is proved, and the agent shares responsibility for the accuracy of the declaration and documents under section 82. A careless agent can therefore expose the importer to penalties for misdeclaration.
Give your agent a written authority, a complete document set and clear instructions on the HS code and value to declare. Ask for copies of the assessment notice, examination report and release order for every consignment. Our article on C&F agent liability explains how responsibility is shared when things go wrong.
An illustrative scenario
Illustrative only; the parties are generic. A Chattogram manufacturer imports a container of machine spare parts. The supplier's invoice describes the goods as "spare parts, assorted". The C&F agent declares a general HS heading with a low duty rate and lodges the bill of entry on the day of unloading.
Customs selects the container for physical examination, the point at which many importers discover what the customs valuation and classification rules demand. The examining officer finds several items that fall under a heading with a higher rate and proposes reassessment. Because the description was vague, the importer cannot quickly show which part belongs where, and port rent starts to run.
The importer's better course would have been to obtain an itemised invoice with part numbers and technical data before shipment, and to consider an advance ruling under section 258 for parts it imports regularly. Having missed that chance, it can pay the reassessed amount under written protest to secure release and pursue a valuation or classification challenge afterwards, rather than leaving the goods to accumulate charges. Anyone learning how to clear goods at Chattogram Custom House should treat the description as part of the legal file, not a formality.
The bill of entry is a legal statement. Whatever your agent types into ASYCUDA World is what customs will hold you to.
Risks and common mistakes
Filing late or leaving goods uncleared
Section 84 sets a five-working-day window from unloading for the bill of entry. Separately, section 94 treats goods as handed over to the government if they are not released within the period the NBR sets, for example because the importer did not make goods available for examination, did not submit mandatory documents or did not pay duties. Goods handed over can be sold or destroyed after notice. Port rent and container detention accrue throughout, so a slow start compounds cost. Our guide to uncleared cargo auctions explains the downstream risk.
Trying to amend the bill of entry too late
Section 86 allows amendments on written request, but not after the importer has been told the goods will be examined, not after an officer establishes that the description is wrong, and generally not after release. Since the Finance Act 2024, quantity, value and description cannot be amended after removal from the customs area except in narrow cases. Spot errors early and apply before examination is ordered. See our guide to bill of entry amendment.
Accepting an HS code you cannot defend
The HS code drives the duty rate, supplementary duty and import restrictions. Agents sometimes choose a code that has cleared before without checking the product. If customs disagrees, the consequence can be reassessment, a penalty for misdeclaration or seizure. Classification disputes are excluded from customs alternative dispute resolution under section 217, so they go through adjudication and appeal. For recurring imports, an advance ruling from the NBR on classification and origin under section 258 binds both the importer and customs officers.
Signing statements at the Custom House without advice
When an examination reveals a discrepancy, officers may ask the importer or agent to sign an explanation or admission. Section 203 allows an order without a show cause notice if the owner admits the offence in writing. That saves time but concedes the facts, and admissions can feed later penalty, money laundering or criminal proceedings. Take advice before signing anything beyond a routine acknowledgement, particularly if the goods may be restricted or the gap between declaration and examination is large.
Ignoring post-clearance exposure
Release is not the end. Section 91 lets an Assistant Commissioner or above reassess classification, origin or value after release, and section 99 allows audit of business records kept under section 246. The general limit for demands is three years from release under section 204, but there is no limit where duty was short-levied because of a false statement. Keep the full clearance file, including correspondence with your agent, for at least that period.
Cross-border and foreign supplier angle
Foreign suppliers and parent companies often assume clearance is the buyer's problem. In practice, the supplier's documents decide how smoothly goods clear at Chattogram. Invoices should show the real price, Incoterm, currency and itemised descriptions. Related-party pricing should be explainable, because section 27 values goods at a price agreed between parties with no interest in each other's business.
Where goods are paid for outside a letter of credit, the payment terms must also fit Bangladesh Bank foreign exchange rules. Our import and export lawyers review supply contracts so that documents, payment and declarations line up. TRW & Co's offices in Dhaka, Singapore, Dubai and London can coordinate with suppliers and their counsel across time zones.
Before the vessel arrives, compare the invoice description, the HS code your agent intends to use and the permit list for that code. Ten minutes spent on this check prevents most of the holds we see at the Chattogram Custom House.
What to do next: a clearance checklist
- Confirm IRC, BIN and any product permits are valid for this consignment.
- Obtain itemised invoices and packing lists with model or part numbers.
- Agree the HS code and declared value with your C&F agent in writing.
- Lodge the bill of entry promptly after unloading, or pre-arrival if eligible.
- Track assessment; if nothing happens within seven working days, consider a section 95 notice.
- Attend or monitor examination and keep copies of every report.
- Pay duties within the stated period to avoid interest at the statutory rate.
- Keep the full clearance file for post-clearance audit.
Learning how to clear goods at Chattogram Custom House is mostly about discipline in documents and deadlines. When a consignment is held, reassessed or seized, early legal input protects both the cargo and your record. Our customs clearance lawyers and seized goods team act at the Custom House and on appeal. You can also start from our Chattogram office hub or contact us at Room 4022, Annex 2, District and Sessions Judge Court Building, Court Hill (Porir Pahar), Kotwali, Chattogram 4000, by email at info@trw.co or on +880 1779 127165.
Frequently asked questions
01How long does customs clearance take at Chattogram port?
There is no fixed overall period. Green-channel consignments with complete documents can move quickly, while goods selected for examination or laboratory testing take longer. The Customs Act 2023 does give importers a lever: if a properly declared consignment is not assessed within seven working days, section 95 allows a notice to the Commissioner, who must then assess or issue a show cause notice. Detained, seized or adjudicated goods are excluded. Port rent and container detention keep running throughout, so plan for possible examination when you set delivery dates.
02Can I clear goods myself without a C&F agent?
The Bangladesh Customs import procedure says the bill of entry may be prepared by a nominated C&F agent or by the importer. In practice most importers at Chattogram use a licensed agent because the agent has ASYCUDA World access, attends examination and deals with port formalities daily. Section 243 of the Customs Act 2023 bars anyone acting as an agent for others without a licence. If you use an agent, give a written authority and keep copies of every document filed in your name.
03What documents are needed for a bill of entry at Chattogram?
The usual set is the commercial invoice, packing list, bill of lading, letter of credit or other payment document, certificate of origin, insurance cover, the importer's IRC and its VAT registration or BIN certificate. Product-specific permits, test reports or quarantine certificates are added where the Import Policy Order or another law requires them. The descriptions, quantities and values must match across all documents. Mismatches are the most common reason a consignment is held for examination or reassessment.
04What happens if customs assesses a higher value than my invoice?
You can provide evidence that the invoice price is the price actually paid, such as the contract, bank payment records and correspondence. If customs maintains its figure, you can pay under written protest to release the goods and then challenge the order through the appeal route, or use alternative dispute resolution for valuation disputes. Under section 93 you may also seek provisional release against a guarantee where enquiries are still pending. Keep everything in writing, because the record you build at assessment is what an appeal will rely on.
05Can I amend a bill of entry after filing it?
Yes, on written request under section 86, provided the amendment is consistent with the original documents. It is not allowed once you have been told the goods will be examined, once an officer has found the description incorrect, or generally after release. Since the Finance Act 2024, quantity, value and description cannot be amended after removal from the customs area except in limited cases. A legitimate substitution of the whole declaration is possible with the Commissioner's permission under section 85.
06What happens to goods that are never cleared?
Under section 94, goods not released within the period set by the NBR can be treated as handed over to the government, for example where the importer failed to present them for examination, submit documents or pay duties. After notice to the owner, customs can sell, destroy or otherwise dispose of them. Perishable goods may be sold at any time with permission. Port and container charges also continue to accrue, so abandoned cargo is usually the most expensive outcome for everyone involved.
Sources and official materials
- Customs Act, 2023 (authentic English text, NBR) — Declarations, assessment, release, agents and appeals
- Bangladesh Customs: import procedure — Bill of entry in ASYCUDA World, documents and release
- Bangladesh Customs — Official customs procedures and trade information
- National Board of Revenue — Customs rules, SROs, general orders and rulings
- NBR introduces new licensing rules for C&F agents (UNB, Jan 2026) — C&F Agent Licensing Regulations 2026
- New Customs Act to take effect on 6 June 2024 (Fibre2Fashion) — Commencement of the Customs Act 2023
General information only, current as at 2 November 2026. It is not legal advice and does not create an advocate–client relationship. It reflects the law of Bangladesh unless stated otherwise, and the law, court practice and official fees change frequently. Check current official sources and take advice on the facts of your matter.