TRW & Co · Banking, Finance & Debt Recovery
Capital Markets Lawyer in Chittagong: Listings, Bonds and Securities Regulation in Chattogram

A capital markets lawyer in Chittagong helps companies raise money from investors, keeps listed companies on the right side of the Bangladesh Securities and Exchange Commission, and resolves disputes with regulators and brokers. New public offer, margin, mutual fund and direct listing rules made in 2025 and 2026 have changed the playbook, and the Chittagong Stock Exchange now recommends IPO approvals.
Key pointUnder the Public Offer of Equity Securities Rules 2025, the stock exchanges give initial approval to IPOs and the BSEC decides on their recommendation, so issuers now need to persuade the exchange first and prepare for two rounds of scrutiny.
At a glance
CSE is based here
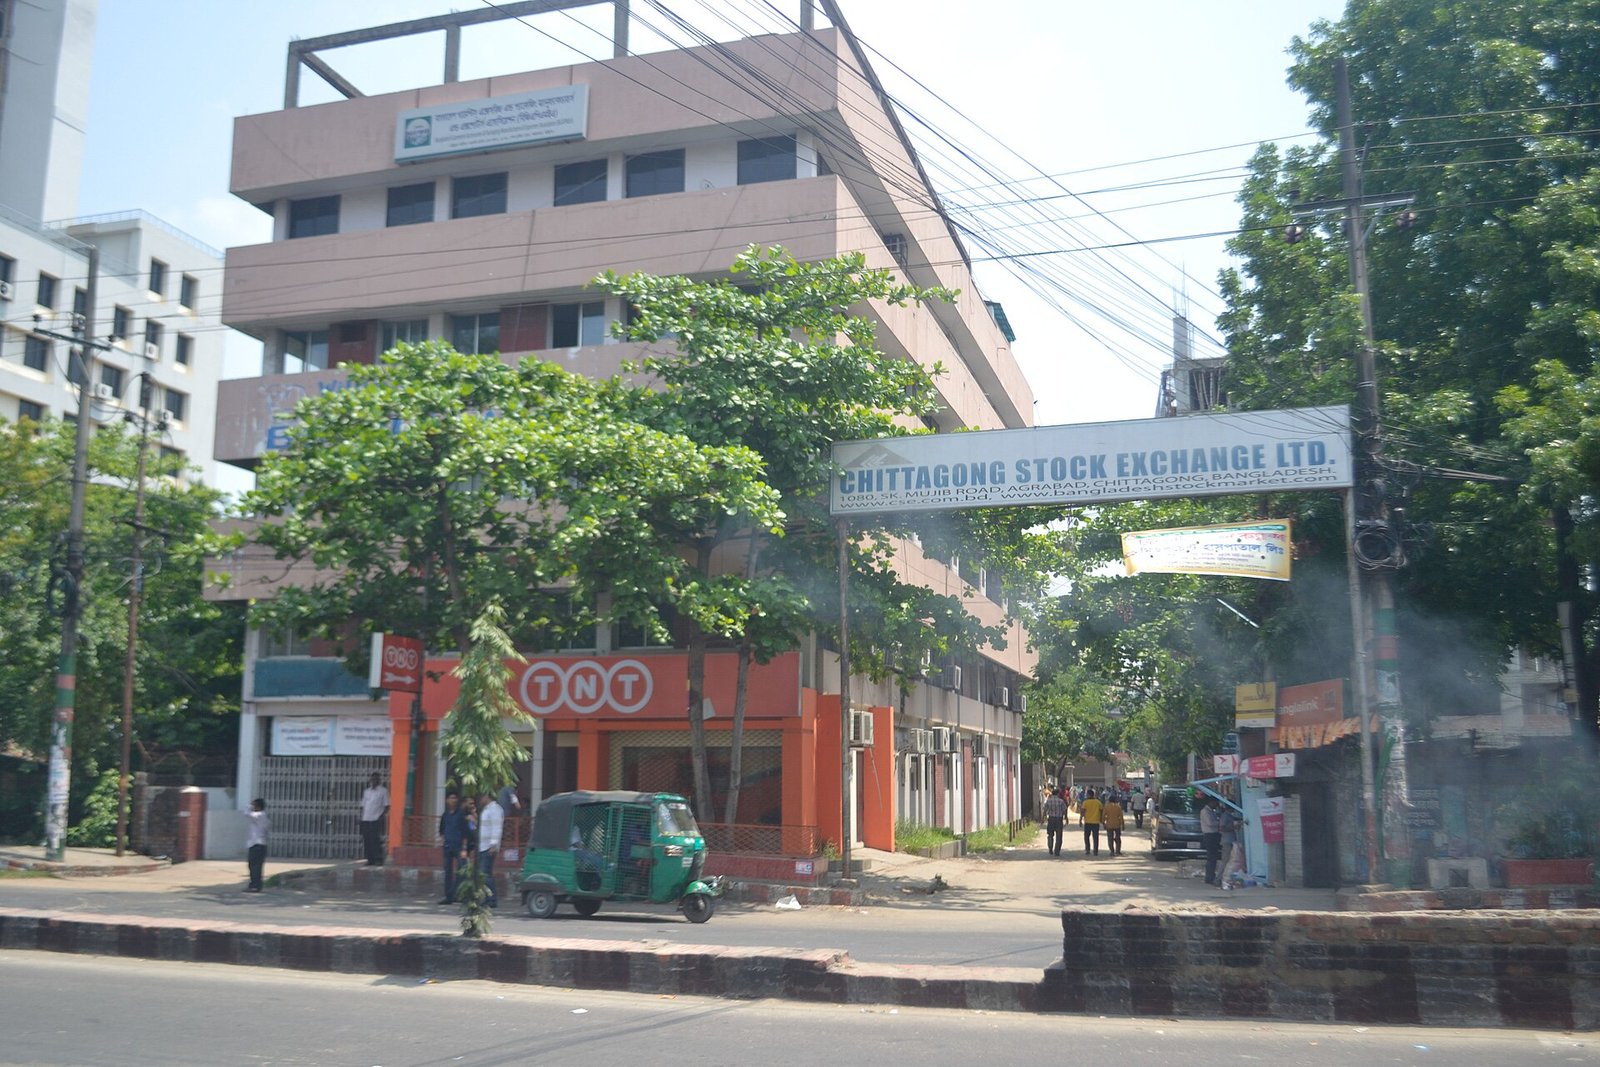
The Chittagong Stock Exchange, authorised in 1995 and demutualised in November 2013, is headquartered in Chattogram and operates under BSEC supervision.
New IPO rules
The BSEC (Public Offer of Equity Securities) Rules 2025, gazetted on 30 December 2025, make exchange recommendation the first step before Commission approval.
Margin rules tightened
The Margin Rules 2025, amended in August 2026, cap financing at 1:1, set a Tk 3 lakh minimum and define call and forced-sale triggers.
Direct listing now possible
The BSEC published Direct Listing of Securities on the Stock Exchange Rules in October 2026, giving companies a listing route without a fresh public offer.
Exchanges regain controls
In July 2026 the BSEC restored the exchanges' authority over circuit breakers and market control measures, withdrawing a 2021 centralising order.
Swipe or scroll →
What a capital markets lawyer in Chittagong handles
A capital markets lawyer in Chittagong advises companies, investors and market intermediaries on raising money from the public, staying compliant once listed, and resolving disputes with regulators, brokers and other shareholders. Chattogram has a particular stake in this work: the Chittagong Stock Exchange (CSE), one of Bangladesh's two stock exchanges, is headquartered in the city, and many of the industrial groups that list or issue bonds have their roots in the port economy.
The work spans equity and debt. On the equity side it covers initial public offerings, qualified investor offers on the SME platform, rights issues, direct listings, takeovers and the ongoing disclosure and governance duties of listed companies. On the debt side it covers bonds, sukuk and privately placed debt securities. Around both sit mutual funds, alternative investment funds, brokers, merchant bankers and custodians, all licensed and supervised by the Bangladesh Securities and Exchange Commission (BSEC).
Capital markets questions rarely arrive labelled as such. A family company planning succession, a lender looking for an exit, a foreign fund buying a stake in a listed manufacturer or an investor whose margin account has been force-sold may all need securities law advice. This page explains the current framework, the routes to market and the disputes we see, alongside our wider banking and finance practice and corporate advisory work.
The legal framework a capital markets lawyer in Chittagong works with
Primary statutes
Bangladesh securities law rests on two core instruments. The Securities and Exchange Ordinance 1969 contains the main conduct rules, including prohibitions on market manipulation and insider dealing and the disclosure duties of issuers. The Bangladesh Securities and Exchange Commission Act 1993 creates the BSEC and gives it rule-making, licensing, inspection and enforcement powers. Parliament amended the 1993 Act in April 2026, removing the age limit for the chairman and commissioners.
Several other statutes sit alongside them. The Depository Act 1999 underpins the electronic holding and transfer of securities through Central Depository Bangladesh Limited. The Exchanges Demutualization Act 2013 separated ownership of the two exchanges from trading rights. The Companies Act 1994 still governs incorporation, share capital, meetings and directors' duties for every listed company, and the Financial Reporting Act 2015 shapes audit and accounting oversight.
Reform is ongoing. The BSEC set up a capital market reform task force in October 2024, and in July 2025 the Financial Institutions Division published a draft law to consolidate the 1969 Ordinance and the 1993 Act, with tougher penalties for manipulation and direct filing of market cases before the special tribunal. Until a consolidated law is enacted, the existing statutes and the rules below govern.
Rules and directives
Most of the day-to-day law sits in rules and directives published on the BSEC laws and regulations page. The most important current instruments include:
- BSEC (Public Offer of Equity Securities) Rules 2025, gazetted on 30 December 2025, which replaced the earlier public issue regime for IPOs.
- BSEC (Direct Listing of Securities on the Stock Exchange) Rules 2026, published in October 2026.
- BSEC (Margin) Rules 2025, issued in November 2025 and amended in August 2026.
- BSEC (Mutual Fund) Rules 2025 and the Alternative Investment Rules 2015 for pooled funds.
- BSEC (Debt Securities) Rules 2021, amended in May 2026, and the Private Placement of Debt Securities Rules 2012.
- Rights Issue Rules 2006, the insider trading prohibition rules of 2022, the takeover rules of 2002 and the whistleblower protection rules made in May 2026.
- The Corporate Governance Code, which applies to listed companies on a comply-or-explain basis for some provisions and mandatorily for others.
A capital markets lawyer in Chittagong has to read these together with exchange listing regulations and the steady flow of BSEC orders and circulars, which often change a deadline or a threshold with immediate effect.
The Chittagong Stock Exchange and why it matters
The CSE was authorised in February 1995, incorporated in April of that year and began floor trading later in 1995. It was demutualised on 21 November 2013 under the 2013 Act and now operates as a public limited company with shareholder directors, independent directors and a strategic investor, subject to BSEC supervision. Its own memorandum, articles, regulations and bye-laws sit alongside BSEC rules, as the exchange explains on its website.
The exchange now plays a larger formal role than before. Under the 2025 public offer rules, the stock exchanges give initial approval to IPO applications and the BSEC grants final approval on the exchanges' recommendations. In July 2026 the BSEC restored the exchanges' authority over circuit breakers and other market control measures, withdrawing a 2021 order that had centralised them at the Commission.
The CSE has also worked for several years on a commodity exchange subsidiary. The legal framework for it was gazetted in 2023, and the CSE has described initial cash-settled products in gold, cotton and crude oil. Anyone planning to trade or broker commodity contracts should check the current registration and product status before committing capital.
In Bangladesh the exchange is no longer just a trading venue. Under the 2025 rules it is the first gate an IPO must pass, which changes how and where an issuer prepares its case.
Routes to market: equity, debt and funds
The right route depends on the issuer's size, track record, investor base and appetite for public scrutiny. A capital markets lawyer in Chittagong will usually compare at least two options before a board commits to one.
| Route | Governing instrument | Typical issuer | Key points |
|---|---|---|---|
| Initial public offering | Public Offer of Equity Securities Rules 2025 | Established companies seeking a main board listing | Exchange recommendation then BSEC approval; minimum paid-up capital and free-float requirements; proceeds to be used within the period the rules set |
| Qualified investor offer | QIO rules and SME platform regulations | Smaller companies | Offered to qualified investors only; trading on the SME platform; eligibility of investors clarified by BSEC in May 2026 |
| Direct listing | Direct Listing Rules 2026 | Companies with an existing shareholder base | Listing without a fresh public offer; new regime, so procedures are still being tested |
| Rights issue | Rights Issue Rules 2006 | Listed companies raising new equity | Prior BSEC consent; disclosure document; underwriting where required |
| Bonds and sukuk | Debt Securities Rules 2021 | Banks, NBFIs, corporates | Public or private; trustee and credit rating; Shari'ah approval for sukuk |
| Funds | Mutual Fund Rules 2025; Alternative Investment Rules 2015 | Asset managers and fund sponsors | Trustee, custodian and asset manager structure; registration with BSEC |
The 2025 rules set a minimum paid-up capital of Tk 30 crore and a minimum public offer of 10 per cent of post-IPO shares, as reported when the rules were gazetted, and require offer proceeds to be used within five years. Issuers below those levels should look at the SME platform, private placement or debt instead. Before choosing, check the gazetted text on the BSEC website, because thresholds are revised regularly.
For many Chattogram groups, debt is the more natural first step. A privately placed bond or a sukuk lets a company build a track record of disclosure, trustee reporting and ratings without the full exposure of an equity listing. It also leaves room for a later IPO once governance structures, audited accounts and related-party arrangements have been tidied up.
How a public offer runs, step by step
Every offer is different, but the sequence below reflects how a capital markets lawyer in Chittagong typically structures an IPO or major debt issue with the issue manager, auditors and the exchange.
- Readiness review. We check the company's constitution, share capital history, title to key assets, licences, tax position, litigation and related-party dealings. Gaps found here are cheaper to fix before the issue manager is appointed.
- Restructuring and governance. Convert to a public limited company if needed, reconstitute the board with independent directors, adopt committee charters and align the articles with the Corporate Governance Code.
- Appointments. Appoint the issue manager, underwriters, auditors from the eligible panel, a credit rating company for debt, and a trustee where required.
- Due diligence and drafting. Prepare the prospectus or information memorandum, legal due diligence report and material contracts schedule. Verify every factual statement against documents.
- Exchange review. File with the CSE and the Dhaka exchange for initial approval under the 2025 rules and answer their queries.
- BSEC approval. Respond to the Commission's observations, satisfy any conditions and obtain consent to the offer.
- Offer, allotment and listing. Run the subscription through the electronic platform, allot securities through the depository, and complete listing formalities with the exchanges.
- Post-listing compliance. Set up disclosure, insider list, dividend and use-of-proceeds reporting from day one, because early lapses attract regulatory attention.
Ongoing duties of listed companies
Listing changes how a company must run itself. Price-sensitive information must be disclosed promptly to the BSEC and the exchanges. Directors and senior staff must not trade on unpublished information, and insider lists and closed periods need to be managed. Quarterly, half-yearly and annual reporting must follow the prescribed format and timetable.
The Corporate Governance Code sets requirements on board composition, independent directors, audit and nomination and remuneration committees, the roles of the managing director, chief financial officer, company secretary and head of internal audit, and certification of compliance. BSEC has also required the appointment of female independent directors and, in July 2026, extended the time for doing so. Our company secretarial team handles the board and filing side of this work.
Dividends are another frequent pressure point. BSEC directives require cash dividends to be kept in a separate bank account and paid within the prescribed time, and unclaimed amounts follow a specific transfer route. Substantial acquisitions of voting shares trigger the takeover rules, so a shareholder building a stake or a group reorganising its holdings needs to plan for disclosure and any offer obligation in advance.
Many enforcement actions begin with a late or incomplete disclosure rather than deliberate wrongdoing. A short internal protocol naming who decides whether information is price-sensitive, and who files it, prevents most problems.
Investor disputes, enforcement and the courts
Margin accounts and broker disputes
The BSEC (Margin) Rules 2025 reshaped margin lending. As amended in August 2026, they limit margin financing to a ratio of 1:1 against the investor's equity, require a minimum secondary market investment of Tk 3 lakh to qualify, restrict eligible securities to A and B category shares meeting a price-earnings test, trigger a margin call when equity falls below 50 per cent of the loan and allow a forced sale at 25 per cent. Disputes about whether a forced sale was properly triggered, notified and executed are common, and they turn on the account agreement, the rules in force on the date and the broker's records.
Regulatory enforcement
The BSEC can inspect, investigate, impose penalties, suspend or cancel registrations, reconstitute boards and issue prohibitory orders against individuals. Its enforcement actions are published. A company or individual facing an inquiry should engage early, preserve documents and make sure responses are accurate, because statements made at the inquiry stage frame everything that follows.
Courts, tribunal and writs
Criminal offences under the securities laws are tried by a special tribunal established for capital market cases. Commission decisions made under statutory powers can be challenged by writ petition in the High Court Division if they are unlawful, procedurally unfair or outside jurisdiction; our writ petition practice explains the threshold. Disputes among shareholders of listed companies may also go to the company bench of the High Court Division, which we cover on our shareholder disputes page.
Risks and common mistakes
Treating the prospectus as a marketing document
The prospectus is a legal document and the directors who sign it are personally exposed if it is untrue or misleading. Forecasts, market share claims and descriptions of litigation or licences must be supported by evidence held on file. We see issues arise most often where a sentence was copied from a pitch deck. A capital markets lawyer in Chittagong will insist on a verification exercise that ties every material statement to a document, a board minute or an expert report, so that the issuer can answer exchange and BSEC queries quickly and defend the document later if challenged.
Leaving related-party arrangements untidy
Family groups often share land, premises, staff, guarantees and trading relationships between companies. Before listing, these arrangements must be documented on arm's-length terms and disclosed. Undocumented loans to directors, guarantees given for sister concerns and informal rent arrangements attract queries from the exchange and the Commission and can delay approval for months. They also become audit issues once the company is listed. Restructuring them early, with board and shareholder approvals in place, is far cheaper than explaining them in the middle of an IPO review.
Missing changes in the rules
The BSEC issues orders, directives and amendments frequently, and many take effect on publication. In 2025 and 2026 alone the regimes for public offers, margin lending, mutual funds, direct listing and whistleblower protection all changed. Advice based on an old version of a rule, or on a summary in the press, is a common source of error. Check the gazetted text and the Commission's latest circulars on the date of each decision, and keep a dated record of which version you relied on.
Building a stake without planning for disclosure
Investors, including foreign funds and strategic buyers, sometimes accumulate shares in a listed company through several entities or brokers without noticing that their combined holding has crossed a disclosure or takeover threshold. Acting in concert is assessed on substance, not on how accounts are labelled. Breaches can lead to penalties and to orders affecting voting rights. Before buying, map all connected holdings and agree how notifications will be made and who is responsible for them.
Responding informally to a BSEC inquiry
An inquiry letter often asks for explanations within a short period. Firms sometimes reply quickly with incomplete information, or let a junior employee answer. That reply becomes part of the record and may later be compared with documents. Take the time to collect the facts, answer precisely, and seek an extension in writing if necessary. Where conduct by individuals is in question, consider whether separate advice is needed for the company and for the people involved.
Foreign investors and Bangladeshis abroad
Foreign portfolio investors can buy listed securities in Bangladesh through a non-resident investor's taka account and a local custodian, under Bangladesh Bank's foreign exchange guidelines. Dividends and sale proceeds can be repatriated once tax and documentation requirements are met. Strategic investors taking larger stakes also need to consider sector caps, the takeover rules and, where new investment is involved, registration with the Invest Bangladesh Authority, which succeeded BIDA under the Invest Bangladesh Act 2026. Our foreign exchange team advises on the banking side.
Non-resident Bangladeshis in the UK, the Gulf and Singapore are an important investor group. They can hold beneficiary owner accounts and invest from abroad, but tax residence, repatriation and the paperwork for powers of attorney are often handled badly. A capital markets lawyer in Chittagong can coordinate those steps with brokers and custodians locally.
TRW & Co's offices in Dhaka, Singapore, Dubai and London help where a deal has a foreign leg: a Singapore holding company investing in a Chattogram manufacturer, a Dubai family office buying listed bank shares, or a London-listed parent reviewing its Bangladeshi subsidiary's disclosure. For wider structuring, see our foreign investment practice and our explainer on acquiring a company in Bangladesh.
How TRW & Co helps as your capital markets lawyer in Chittagong
We work with issuers, investors, intermediaries and boards from our Chattogram office, with support from Dhaka for filings and hearings. Typical workstreams include:
IPO and listing readiness
Legal health checks, corporate restructuring, board and committee set-up, and legal due diligence for prospectuses under the 2025 public offer rules. We work alongside the issue manager rather than duplicating its role.
Bonds and sukuk
Structuring and documenting public and private debt issues, trust deeds, security packages and Shari'ah documentation, and liaising with trustees and rating agencies on conditions.
Listed company compliance
Disclosure protocols, insider trading policies, Corporate Governance Code compliance reviews, dividend and AGM processes, and responses to exchange and Commission queries.
Stakes and takeovers
Advice on acquiring or selling significant holdings, takeover rules, shareholder agreements and the M&A process for listed and unlisted targets.
Enforcement and inquiries
Representation in BSEC inquiries and hearings, preparation of written submissions, and coordination with criminal counsel where tribunal proceedings are possible.
Investor and broker disputes
Margin account and forced-sale disputes, claims against intermediaries, writ challenges to regulatory decisions and arbitration where agreements provide for it.
We do not give investment advice or recommend securities. Our role is legal: structure, documents, compliance and disputes. To discuss a matter, contact our Chattogram office or see all our practices and the Chattogram office overview.
Checklist for boards and investors
- Identify the right route (IPO, QIO, direct listing, debt or private placement) and confirm current thresholds in the gazetted rules.
- Run a legal readiness review covering title, licences, tax, litigation and related-party arrangements before appointing advisers.
- Restructure the board and committees to meet the Corporate Governance Code, including independent and female independent directors.
- Build a verification file supporting every material statement in the offer document.
- Adopt disclosure, insider trading and whistleblower procedures before listing, not after.
- For investors, map connected holdings against takeover and disclosure thresholds before buying.
- For margin clients, keep copies of the account agreement, margin calls and trade confirmations.
- For foreign investors, set up the custodian, taka account and tax documentation before the first trade.
- Diary BSEC deadlines and check for new orders and circulars on the date of each decision.
For related reading, see our guides to shareholders agreements, directors duties and AML compliance in Bangladesh, and our due diligence practice.
Frequently asked questions
01Who regulates the capital market in Bangladesh?
The Bangladesh Securities and Exchange Commission regulates issuers, stock exchanges, the depository, brokers, dealers, merchant bankers, asset managers, custodians and credit rating companies. Its powers come mainly from the Securities and Exchange Ordinance 1969 and the Bangladesh Securities and Exchange Commission Act 1993, together with the Depository Act 1999 and the Exchanges Demutualization Act 2013. The Dhaka and Chittagong stock exchanges have their own regulations and, under the 2025 public offer rules, make the first recommendation on IPO applications.
02Can a Chattogram company list only on the Chittagong Stock Exchange?
Listing decisions are made under the BSEC's public offer rules and the listing regulations of each exchange, and in practice most issuers apply to both the Chittagong and Dhaka exchanges so that their shares trade on both. The 2025 rules give the exchanges a formal role in recommending approval. Whether a single-exchange listing is possible or advisable depends on the route chosen and the current rules, so it should be checked against the gazetted text before the issue manager starts work.
03What are the minimum requirements for an IPO under the 2025 rules?
When the Public Offer of Equity Securities Rules 2025 were gazetted on 30 December 2025, they were reported to require at least Tk 30 crore of paid-up capital, an offer of at least 10 per cent of post-IPO shares, and use of the proceeds within five years. There are also requirements on audited accounts, governance, disclosure and the issue manager's role. Thresholds can be amended by the BSEC, so a capital markets lawyer in Chittagong will confirm the current version before you plan.
04My broker force-sold my shares. Do I have a claim?
Possibly. The Margin Rules 2025, as amended in August 2026, set when a margin call is triggered, how long the client has to top up and when a forced sale is allowed. Whether a claim exists depends on the rules in force on the dates in question, the margin agreement, the notices actually sent and the prices achieved. Collect your account statements, margin call messages and trade confirmations, and seek advice quickly, because complaints are easier to pursue while records are fresh.
05How can a foreign investor buy listed shares in Bangladesh?
Foreign portfolio investors usually open a beneficiary owner account with a local custodian and a non-resident investor's taka account with an authorised bank, then trade through a licensed broker. Bangladesh Bank's foreign exchange guidelines govern inward remittance and repatriation of dividends and sale proceeds. Larger strategic stakes also raise takeover, disclosure and sector-specific issues, and new direct investment may require registration with the Invest Bangladesh Authority, which succeeded BIDA in 2026.
06What happens if the BSEC opens an inquiry into my company?
The Commission can call for documents, examine officers, appoint inquiry teams and, after giving an opportunity to be heard, impose penalties, issue directions or take other action. Treat the first letter seriously: preserve records, establish the facts internally, and respond accurately within the time given or seek an extension in writing. Decisions made outside the Commission's powers or without a fair hearing can be challenged by writ petition in the High Court Division.
07Are bonds a better first step than an IPO?
For many companies, yes. A privately placed bond or sukuk under the Debt Securities Rules 2021 raises funds while building a record of disclosure, trustee reporting and credit rating, without immediately opening the company to public shareholders. It suits groups with steady cash flows and assets but untidy governance. The trade-off is fixed repayment obligations and covenants. A capital markets lawyer in Chittagong will compare cost, timing and control under each route before a board decides.
Sources and official materials
- Bangladesh Securities and Exchange Commission: Act, Rules and Regulations — Official list of securities laws, rules, orders and directives
- Bangladesh Securities and Exchange Commission — Regulator's website, enforcement actions and press releases
- Chittagong Stock Exchange: Inside CSE — History, demutualisation and governance of the CSE
- IPO rulebook overhauled (UNB) — Key terms of the Public Offer of Equity Securities Rules 2025
- Revised margin rules gazetted (Financial Express, August 2026) — Ratios, eligibility and forced-sale triggers under the amended Margin Rules
- Central Depository Bangladesh Limited — Depository for electronic securities under the Depository Act 1999
- Invest Bangladesh Authority — Investment agency that succeeded BIDA under the 2026 Act
General information only, current as at 27 October 2026. It is not legal advice and does not create an advocate–client relationship. It reflects the law of Bangladesh unless stated otherwise, and the law, court practice and official fees change frequently. Check current official sources and take advice on the facts of your matter.