TRW & Co · Banking, Finance & Debt Recovery
Banking Lawyer in Chittagong (Chattogram): Lending, Security and Recovery

A banking lawyer in Chittagong advises lenders, borrowers and guarantors on loans, security, recovery and Bangladesh Bank regulation in the country's trading capital. Since 2025, bank resolutions, new rescheduling facilities, wilful defaulter rules and new commercial courts have reshaped the field, so advice written before then may no longer describe your real options.
Key pointMost Chattogram banking disputes are won or lost on documents signed years earlier and on whichever Bangladesh Bank rescheduling or exit window is open at the time, so reconciling the account and checking the current circular come before any court strategy.
At a glance
Layered legal framework
The Bank Company Act 1991, Bangladesh Bank Order 1972, Finance Company Act 2023 and Artha Rin Adalat Ain 2003 work together with central bank circulars.
Bank resolution powers
The Bank Resolution Ordinance 2025 lets Bangladesh Bank appoint administrators, transfer assets and liabilities, and create bridge banks for failing banks.
Wilful defaulter regime
Listed wilful defaulters face requests for travel bans and licence restrictions, cannot reschedule, and are barred from bank boards for five years.
Ten-year rescheduling window
Bangladesh Bank's 2025 special policy support allowed rescheduling for up to ten years with a two-year grace period, with terms changed repeatedly since.
Movable assets as collateral
The Secured Transactions (Movable Property) Act 2023 lets traders offer stock, receivables and equipment as security, not only land.
Swipe or scroll →
What a banking lawyer in Chittagong does
A banking lawyer in Chittagong advises banks, finance companies, borrowers, guarantors and investors on the law that governs lending, security, recovery and regulatory compliance in Bangladesh's commercial capital. The work runs from drafting a facility agreement and registering a mortgage to defending a Money Loan Court suit, negotiating a rescheduling, or responding to a Bangladesh Bank inspection.
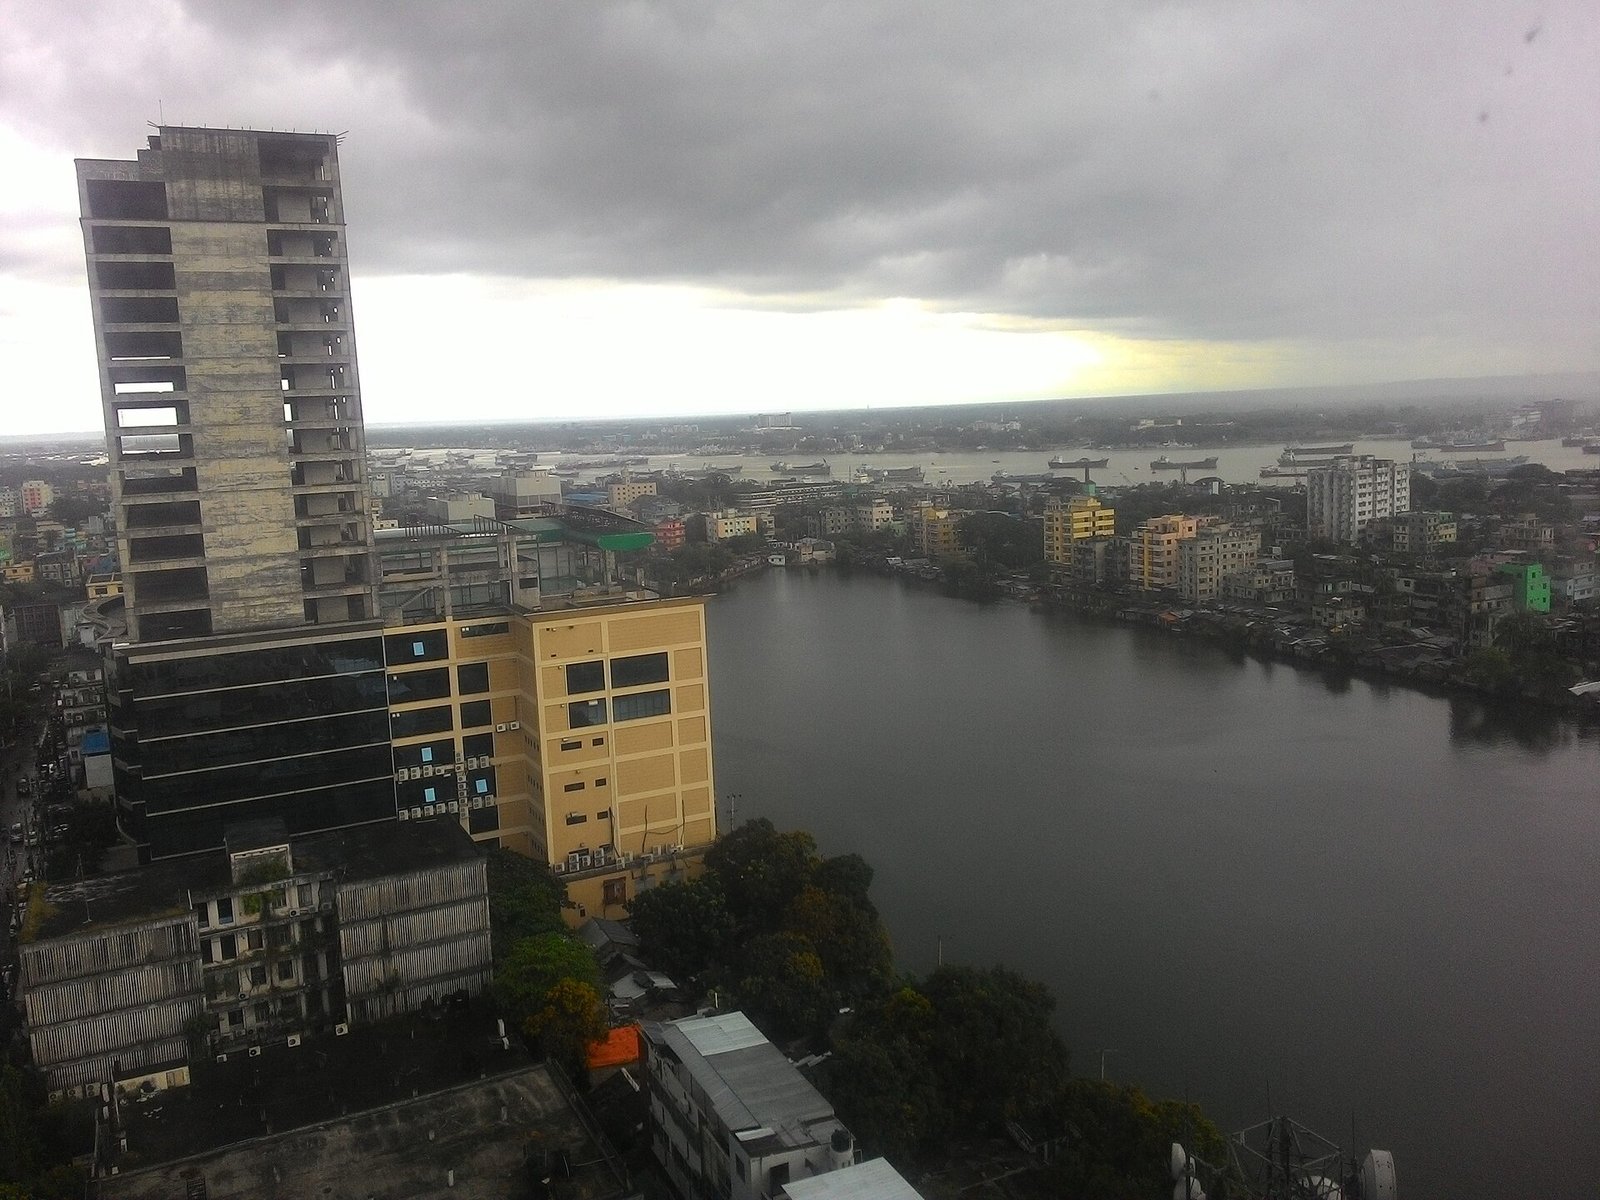
Chattogram is where a large share of the country's trade credit is written and, when things go wrong, where it is fought over. The trading houses of Khatunganj and Asadganj, the bank branches clustered in Agrabad, the steel, cement, edible-oil, ship-recycling and garment businesses along the Dhaka-Chattogram highway and the Karnaphuli, and the importers who move goods through the port all depend on working capital, letters of credit and term loans.
That concentration of credit means that banking questions in Chattogram rarely stay theoretical. A missed instalment becomes a classified loan, a classified loan becomes a demand notice, and a demand notice can become an auction of a factory or family home. Good advice at the documentation stage prevents many of these disputes, and good advice at the first sign of stress often decides how they end.
The legal and regulatory framework for banking in Bangladesh
Banking in Bangladesh is governed by a layered set of statutes, central bank regulations and court practice. A banking lawyer in Chittagong has to read all three together, because a circular issued in Dhaka can change the value of a loan book in Agrabad overnight.
Core statutes
- Bank Company Act 1991. The principal law for scheduled banks: licensing, ownership, directors, lending limits, related-party exposure and the central bank's supervisory powers. Its 2023 amendment introduced a formal regime for wilful defaulters.
- Bangladesh Bank Order 1972. Establishes Bangladesh Bank as the central bank and regulator, with power to issue binding directions through its departments' circulars.
- Finance Company Act 2023. Governs non-bank financial institutions and repealed the Financial Institutions Act 1993.
- Bank Resolution Ordinance 2025. Published in May 2025, it gives Bangladesh Bank powers to appoint temporary administrators, transfer a weak bank's shares, assets and liabilities, and set up bridge banks.
- Artha Rin Adalat Ain 2003. The Money Loan Courts Act, which gives special courts exclusive jurisdiction over recovery suits by financial institutions.
- Secured Transactions (Movable Property) Act 2023. Allows movable assets such as inventory and receivables to be used as collateral, a significant change for traders who hold little land.
- Money Laundering Prevention Act 2012. Imposes customer due diligence, monitoring and suspicious transaction reporting duties, supervised by the Bangladesh Financial Intelligence Unit.
- Other laws that matter daily. The Negotiable Instruments Act 1881 (cheques and bills), the Transfer of Property Act 1882 (mortgages), the Contract Act 1872 (guarantees), the Bankers' Books Evidence Act 2021 (digital bank records as evidence), the Payment and Settlement Systems Act 2024, the Foreign Exchange Regulation Act 1947 and the Companies Act 1994 (corporate borrowers, charges and winding up).
Regulators and courts
Bangladesh Bank supervises banks through its departments in Dhaka and its regional offices, including in Chattogram. Its foreign exchange rules for trade, investment and borrowing abroad are consolidated in the Guidelines for Foreign Exchange Transactions, as amended by later circulars. Bangladesh Bank's FEPD circular no. 40 of 30 September 2026 reflects that BIDA has been succeeded by the Invest Bangladesh Authority under the Invest Bangladesh Act 2026, which matters for foreign-owned borrowers.
Disputes go to several forums. Recovery suits by banks are heard by the Artha Rin Adalats sitting within the Chattogram court complex. Cheque prosecutions go to the Chattogram magistracy and Sessions courts. Winding up, company matters and writ petitions against regulators or banks go to the High Court Division in Dhaka. Court information and cause lists are published by the Chattogram district judiciary.
Why banking law in Chattogram looks different in 2026
The past two years have changed the landscape more than the previous decade. Clients who rely on older advice risk getting both the law and the bank's negotiating position wrong.
Bank resolution. Under the Bank Resolution Ordinance 2025, Bangladesh Bank declared five Shariah-based banks (EXIM Bank, First Security Islami Bank, Global Islami Bank, Social Islami Bank and Union Bank) failed institutions, appointed administrators in November 2025 and moved them into a merged entity, Sammilito Islami Bank. Many Chattogram borrowers and depositors had relationships with those banks, so questions about who now holds the loan, the security and the deposit are live.
Defaulted loans. Classified loans reached a reported Tk 6.44 trillion, around 36 per cent of total loans, by the end of September 2025. In response, Bangladesh Bank introduced special policy support for distressed borrowers in 2025, allowing rescheduling for up to ten years including a two-year grace period, and then repeatedly adjusted down payments and extended deadlines through 2026.
Wilful defaulters. Following the 2023 amendment to the Bank Company Act, Bangladesh Bank directed banks to set up units to identify wilful defaulters. A person listed as a wilful defaulter faces requests for travel bans and restrictions on trade licences and company registration, cannot have interest waived or the loan rescheduled, and is barred from bank and finance company boards for five years after removal from the list.
Commercial courts. The Commercial Courts Act 2026, passed on 7 April 2026, expressly leaves bank recovery suits within the Artha Rin Adalat's jurisdiction. Other banking-related commercial disputes may, however, go to the new courts; the official cause-list portal lists two for Chattogram Metropolitan and one for the district.
In Chattogram, the outcome of a banking dispute is usually decided by the paperwork signed years earlier and the regulatory window open today, not by the speech made at the final hearing.
Key decisions for lenders and borrowers
Most banking mandates come down to a small number of strategic choices. A banking lawyer in Chittagong should set them out early, with the costs and risks of each, rather than defaulting to litigation.
| Route | Main legal basis | Best suited to | Main risk |
|---|---|---|---|
| Rescheduling or restructuring | Bangladesh Bank circulars; bank board approval | Viable businesses with a temporary cash-flow problem | Breach of new terms revives full recovery action |
| Negotiated settlement or exit | Contract; Bangladesh Bank exit and write-off rules | Borrowers who can sell assets or refinance | Settlement not documented as a consent decree or release |
| Sale of mortgaged property without suit | Artha Rin Adalat Ain 2003, section 12 | Banks holding a registered mortgage with power of sale | Irregular notice or valuation invites a challenge |
| Money Loan Court suit | Artha Rin Adalat Ain 2003 | Contested or high-value recoveries | Delay; backlog in the Chattogram courts |
| Cheque prosecution | Negotiable Instruments Act 1881 | Dishonoured security or repayment cheques | Running it without a coherent recovery plan |
| Winding up or insolvency | Companies Act 1994; Bankruptcy Act 1997 | Insolvent companies or individuals with dissipating assets | Slow; secured creditors may gain little extra |
Banks pursuing recovery will usually combine routes, for example a section 12 sale notice alongside a cheque case and a suit against guarantors. Our pages on the Money Loan Court and debt recovery explain those tools in more depth. Borrowers should read our page on loan settlement and rescheduling before they respond to a demand.
Lending transactions and security in Chattogram
Banking work is not only about disputes. Much of the value a banking lawyer in Chittagong adds lies in getting the documents right at the start, so that security can actually be enforced if the borrower fails.
Mortgages of land and buildings
Most commercial lending in Chattogram is still secured on land. A registered mortgage with a power of sale gives the bank the fastest route to recovery, but only if title is clean. Title in Chattogram can be complicated by inherited shares, unrecorded transfers, CDA lease terms and gaps in the khatian. Our title verification team checks the chain of title, mutation and land development tax before a mortgage is taken.
Movables, receivables and stock
The Secured Transactions (Movable Property) Act 2023 opened a route for traders and manufacturers who hold stock, receivables and equipment rather than land. For Chattogram's commodity traders, whose wealth often sits in goods in warehouses and in transit, a properly registered security interest over inventory can be more realistic than a mortgage.
Guarantees and corporate charges
Personal guarantees from directors and family members are standard. Charges created by companies must be registered with the RJSC under the Companies Act 1994, and an unregistered charge can fail against a liquidator or other creditors. Syndicated and club facilities, common for steel and power projects around Chattogram, need clear intercreditor terms on enforcement and sharing.
How a banking matter typically runs
Every file is different, but most banking mandates in Chattogram follow a recognisable sequence. The steps below assume a loan under stress, which is where most clients first call us.
- Collect and read the documents. Sanction letters, facility agreements, security documents, guarantees, statements of account, CIB reports and all correspondence. Gaps and inconsistencies are often the most valuable findings.
- Reconcile the account. Check interest, penal charges, suspense accounts and classification status against the documents and current Bangladesh Bank rules. Disputed figures shape every later step.
- Map the security and the parties. Identify every mortgaged property, hypothecated asset, guarantor and cheque, and verify title and registration so that both sides understand what is really at stake.
- Check the regulatory window. Confirm which rescheduling, restructuring, exit or write-off rules apply at that date, and whether wilful defaulter or fraud allegations close any of them.
- Choose the route. Decide between negotiation, a section 12 sale, a Money Loan Court suit, a cheque prosecution, a writ or insolvency, or a combination, with a realistic budget and timetable.
- Negotiate or litigate. Run settlement talks with authority from the bank's head office or the borrower's board, while preserving legal positions in court.
- Document the outcome. Record any settlement as a consent decree, rescheduling agreement or release, update the CIB position and release or re-register security.
Bangladesh Bank's special rescheduling and exit facilities have been issued, amended and extended several times since 2025, each with its own cut-off dates and down payment terms. Before relying on any facility, obtain the current circular and confirm with the bank that it applies to your loan's classification date. A position that was available last quarter may already have closed.
Documents and evidence to assemble
Whether you are a bank or a borrower, the first meeting with a banking lawyer in Chittagong is far more productive if the following are ready:
- Sanction letters, facility agreements and every renewal, enhancement or rescheduling letter
- Mortgage deeds, irrevocable powers of attorney, hypothecation and pledge documents, and title deeds with khatians and mutation records
- Personal and corporate guarantees, board resolutions and RJSC charge filings
- Statements of account from disbursement, interest calculations and any suspense or blocked accounts
- Credit Information Bureau reports and the bank's classification history
- Demand notices, legal notices, section 12 sale notices and any auction advertisements
- Undated or security cheques given to the bank, and any cheque case papers
- For trade facilities: LCs, bills of exchange, import documents and trust receipts (see our trade finance page)
Under the Bankers' Books Evidence Act 2021, certified bank records, including digital records, are admissible. Borrowers should therefore test the bank's figures early rather than assuming the court will not rely on them.
Risks and common mistakes in Chattogram banking matters
Ignoring the first demand notice
Borrowers often treat a demand notice as routine. It rarely is. It may be the step that starts a section 12 sale under the Artha Rin Adalat Ain 2003, or the foundation of a cheque case. Silence also weakens any later argument that the bank's figures were wrong. A short, accurate reply that disputes incorrect charges and proposes a realistic path keeps options open, and it creates a record that matters if the dispute reaches court. A banking lawyer in Chittagong can usually prepare that reply within days.
Assuming the land security is clean
Banks sometimes discover at enforcement that mortgaged land is subject to co-sharers' claims, earlier transfers, acquisition proceedings or record errors. Auction buyers then hesitate and recoveries fall. For lenders, title due diligence before disbursement is cheap compared with years of litigation. For borrowers and third-party mortgagors, defects in title or in the mortgage itself can be a legitimate defence, but they must be raised promptly and with evidence. Our land lawyers work alongside the banking team on these questions.
Settling without proper documentation
Oral understandings with branch officials are a common source of later disputes. A settlement that is not approved at the right level within the bank, recorded in writing and, where a suit is pending, embodied in a consent decree can be disowned. Borrowers should also insist on written confirmation of the release of security, the return of cheques and the correction of their CIB status. Banks, for their part, should ensure any compromise fits Bangladesh Bank's provisioning and write-off rules so it survives an inspection.
Running parallel cases without a plan
Banks in Chattogram often file a Money Loan Court suit, a cheque prosecution and sometimes a criminal complaint at the same time. Done well, parallel proceedings create leverage. Done badly, they create contradictory pleadings, duplicate costs and arguments about double recovery. Borrowers face the mirror problem: defending several cases with different lawyers who never speak to each other. One coordinated strategy, with a clear view of which case drives settlement, is almost always better.
Underestimating regulatory and AML exposure
Loan disputes increasingly overlap with money laundering and fraud inquiries. If a bank or investigator alleges that loan proceeds were diverted, or that trade documents were false, the matter can involve the BFIU, the Anti-Corruption Commission or the CID. Statements made in a civil negotiation can be used elsewhere. Borrowers facing those allegations need coordinated civil and criminal advice; see our money laundering defence page.
Cross-border, NRB and foreign lender issues
Chattogram's banking disputes frequently cross borders. Non-resident Bangladeshis in the UK, the Gulf and Singapore often stand as guarantors or own mortgaged family property in the city, and may only learn of a suit when a relative sends them a newspaper auction notice. Our NRB practice acts for clients abroad through properly executed powers of attorney and video conferences.
Foreign lenders and suppliers that instruct a banking lawyer in Chittagong face different questions: whether a Bangladeshi borrower can lawfully pay, whether Bangladesh Bank approval is needed for foreign borrowing or remittance, and how to enforce a foreign judgment or arbitral award against assets in Chattogram. Foreign-owned borrowers must also keep their investment registration current with the Invest Bangladesh Authority.
TRW & Co's offices in Dhaka, Singapore, Dubai and London help coordinate these matters. Dhaka handles High Court Division filings and central bank liaison; Singapore, Dubai and London help counterparties and NRB clients in their own time zones and coordinate with local counsel on foreign proceedings.
How a banking lawyer in Chittagong at TRW & Co helps
Our Chattogram team at Room 4022, Annex 2, District and Sessions Judge Court Building, Court Hill (Porir Pahar), Kotwali, Chattogram 4000, works with banks, finance companies, corporate borrowers, guarantors and investors. The firm's Bangladesh advocates appear in the Chattogram courts and tribunals and, through our Dhaka team, in the High Court Division.
Lending and security documents
We draft and review facility agreements, mortgages, hypothecations, guarantees and security over movables, and check title and corporate authority before disbursement so that the security can be enforced later.
Recovery for lenders
We advise on demand notices, section 12 sales, Money Loan Court suits, execution and cheque prosecutions, choosing the combination that gives the best realistic recovery against each borrower and guarantor.
Borrower and guarantor defence
We test the bank's figures and documents, defend suits and auctions, and negotiate rescheduling, restructuring or exit under the Bangladesh Bank rules in force at the time.
Regulatory and compliance
We advise on Bangladesh Bank directions, wilful defaulter listings, AML and KYC duties, foreign exchange questions and responses to inspections, coordinating with our Dhaka office on matters before the central bank.
Trade and working capital
We advise importers, exporters and banks on LCs, bank guarantees, bills of exchange and trust receipts, which drive much of Chattogram's credit risk.
Writs and appellate work
Where a regulator, bank or auction process acts unlawfully, we assess writ petitions and appeals in the High Court Division, alongside our writ practice.
We do not promise outcomes, and we tell clients early when the documents or the regulatory window make a particular route unrealistic. To discuss a matter, see our contact page or browse all our practices and the Chattogram office overview.
Checklist for decision-makers
- Do we have every facility, security and guarantee document, including renewals and rescheduling letters?
- Has the account been independently reconciled, including interest, penal charges and classification dates?
- Is title to every mortgaged property verified, and are company charges registered with the RJSC?
- Which Bangladesh Bank rescheduling, exit or write-off rules apply today, and when do they close?
- Has anyone alleged fraud, diversion or wilful default that could close regulatory options or trigger criminal exposure?
- Are parallel proceedings (suit, cheque case, auction, writ) coordinated by one strategy and one team?
- For NRBs and foreign parties: are powers of attorney, foreign exchange approvals and enforcement plans in place?
- Is any settlement approved at the right level and recorded as a consent decree, rescheduling agreement or release?
If several of those answers are uncertain, speak to a banking lawyer in Chittagong before the next deadline rather than after it. Early, specific advice is usually the cheapest advice a lender or borrower will buy.
Frequently asked questions
01When should a business in Chattogram call a banking lawyer?
Ideally before signing a facility or security document, and certainly at the first sign of repayment stress: a missed instalment, a classification notice, a demand letter or a request for further security. At that stage there are usually several options, including rescheduling, restructuring, refinancing or a negotiated exit. Once a section 12 sale notice is published or a Money Loan Court suit is filed, options narrow and deposits may be required to challenge decisions. Early review of the documents and the account is far cheaper than defending an auction.
02Can a bank sell my mortgaged property without going to court?
Yes, in some cases. Section 12 of the Artha Rin Adalat Ain 2003 allows a financial institution holding a mortgage with a power of sale to sell the property by auction without first obtaining a decree, after giving the required notices. The borrower and mortgagor can still challenge an irregular sale, for example where notices were defective, the valuation was unreasonable or the debt figure is wrong. Timing matters, so take advice as soon as a sale notice appears.
03What is a wilful defaulter and what are the consequences?
After the 2023 amendment to the Bank Company Act 1991, a wilful defaulter is broadly a borrower who can repay but does not, or who obtained credit by fraud or false information, used the loan for another purpose, or transferred pledged collateral without consent. Bangladesh Bank asks authorities to impose travel bans and restrict trade licences and company registration. Wilful defaulters cannot reschedule or obtain interest waivers and are barred from bank and finance company boards for five years after removal from the list.
04Does the new Commercial Courts Act 2026 apply to bank loan cases?
Bank and financial institution recovery suits remain within the exclusive jurisdiction of the Artha Rin Adalat under the Artha Rin Adalat Ain 2003; the Commercial Courts Act 2026 expressly leaves those matters out. Other banking-related commercial disputes, such as some contract claims between businesses, may fall within the new commercial courts, which are now listed for Chattogram. The government has signalled amendments to the 2026 Act, so check the current position for each dispute.
05My loan was with one of the merged Islamic banks. Who do I deal with now?
Under the Bank Resolution Ordinance 2025, EXIM Bank, First Security Islami Bank, Global Islami Bank, Social Islami Bank and Union Bank were declared failed institutions and placed into resolution, with their business moving to Sammilito Islami Bank. Loans, security and deposits generally follow the transferred business, but borrowers should confirm in writing which entity holds their facility, their security documents and any pending case, and ensure that payments and settlements are made to and approved by the correct entity.
06Can a non-resident Bangladeshi deal with a Chattogram bank case from abroad?
Yes. Guarantors and owners of mortgaged property living in the UK, the Gulf or Singapore can act through a properly executed and authenticated power of attorney, give instructions remotely and, where needed, travel only for key hearings or signings. The important step is to act quickly once you learn of a demand, auction notice or suit, because deadlines run regardless of where you live. TRW & Co coordinates such matters between Chattogram and our offices abroad.
07Can I use stock or receivables as security instead of land?
Yes. The Secured Transactions (Movable Property) Act 2023 allows businesses to grant security interests over movable assets such as inventory, receivables and equipment, with registration to establish priority. For Chattogram traders whose main assets are goods and book debts, this can open access to credit. Lenders should check the registry and the asset description carefully, and borrowers should understand the enforcement rights they are giving the bank.
Sources and official materials
- Artha Rin Adalat Ain 2003 (Bangladesh Laws) — Money Loan Courts Act: suits, sales and execution
- Bangladesh Bank — Central bank circulars on classification, rescheduling and foreign exchange
- Bangladesh Financial Intelligence Unit — AML and CFT supervision and guidance
- Guidelines for Foreign Exchange Transactions 2018 — Foreign exchange rules for trade, investment and borrowing
- Companies Act 1994 (Bangladesh Laws) — Corporate borrowers, charges and winding up
- Supreme Court of Bangladesh — High Court Division writs, company matters and appeals
- Chattogram District Judiciary — Chattogram courts and cause lists
General information only, current as at 2 November 2026. It is not legal advice and does not create an advocate–client relationship. It reflects the law of Bangladesh unless stated otherwise, and the law, court practice and official fees change frequently. Check current official sources and take advice on the facts of your matter.